Mortgage Rates Ease Ahead of the Fed's October Decision: What Homebuyers and Real Estate Investors Need to Know
Understanding the Impact of Recent Mortgage Rate Declines on Homebuyers and Real Estate Investors

A Small Drop in Mortgage Rates Offers Some Relief, but Affordability Remains a Challenge
Mortgage rates have finally moved slightly lower, offering a little relief to prospective homebuyers and real estate investors. However, with borrowing costs still elevated compared with a year ago, the latest decline is a reminder that the real estate market continues to require careful financial planning.
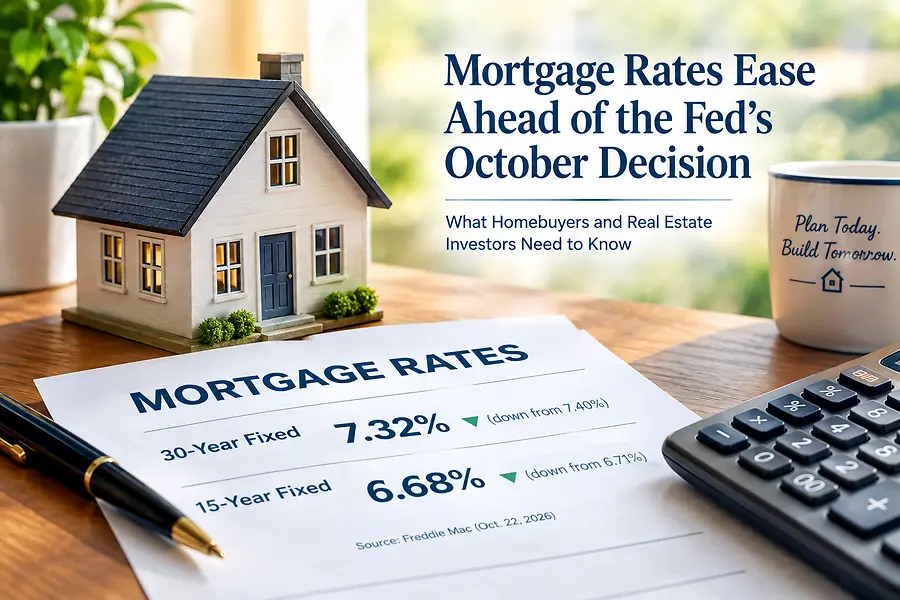
According to Freddie Mac's October 22, 2026, mortgage market report, the average 30-year fixed mortgage rate fell to 7.32%, down from 7.40% the previous week. The average 15-year fixed mortgage rate also declined to 6.68%, compared with 6.71% a week earlier.
Although these reductions are encouraging, today's rates remain significantly higher than they were a year ago, when the average 30-year fixed mortgage rate stood at 6.19%.
For buyers who have been waiting for more favorable financing conditions, the question is whether this decline signals a larger downward trend or simply a temporary pause in a volatile interest-rate environment.
The answer will depend on several economic factors, including inflation, Treasury yields, and the Federal Reserve's monetary policy decisions.
What Can We Expect From the Federal Reserve?
The Federal Reserve is scheduled to meet October 27–28, with its next interest-rate decision expected on Wednesday, October 28.
At its September meeting, the Fed raised its benchmark federal funds rate by a quarter of a percentage point, bringing the target range to 3.75%–4.00%. The decision reflected continued concerns about inflation and the need to bring price increases closer to the Fed's long-term 2% objective.
This upcoming meeting is particularly important because investors, homebuyers, and real estate professionals are watching closely for clues about the direction of borrowing costs.
However, there is an important distinction to understand: The Federal Reserve does not directly set mortgage rates.
Mortgage rates are influenced by a combination of factors, including the 10-year U.S. Treasury yield, inflation expectations, investor demand for mortgage-backed securities, and broader financial-market conditions.
Consequently, even if the Fed holds its benchmark rate steady, mortgage rates could rise or fall depending on how financial markets respond to economic developments and the Fed's statements.
For buyers and investors, this means a Federal Reserve announcement should be viewed as one part of the larger financial picture—not a guarantee that mortgage rates will immediately decline.
How Higher Mortgage Rates Affect Home Affordability
Mortgage rates have a direct effect on purchasing power. When interest rates increase, buyers generally qualify for smaller loans if their incomes, debts, and other financial circumstances remain unchanged.
Consider a hypothetical buyer financing a $300,000 home with a $240,000, 30-year fixed-rate mortgage.
At an interest rate of 6.19%, the estimated monthly principal and interest payment would be approximately $1,464.
At 7.32%, that payment would increase to approximately $1,647.
That is a difference of about $183 per month, or approximately $2,196 annually.
These figures exclude property taxes, homeowners insurance, mortgage insurance, and homeowners association fees, which can add substantially to the total monthly housing expense.
For households already managing higher living costs, that difference can determine whether a property fits within their budget.
Higher borrowing costs can also affect sellers. When buyers have less purchasing power, properties may take longer to sell, and sellers may need to reconsider their asking prices, offer concessions, or explore alternative financing arrangements.
For real estate professionals, understanding these dynamics is essential when helping clients evaluate properties and structure transactions.
What Does This Mean for Real Estate Investors?
For real estate investors, the current market presents both challenges and opportunities.
Higher financing costs can reduce cash flow, make some acquisitions less attractive, and increase the importance of careful underwriting. However, changing market conditions can also create opportunities for investors who understand their numbers and have access to appropriate financing.
Rather than relying on the possibility of lower rates in the future, investors should evaluate each acquisition using current financing terms.
Several factors deserve particular attention:
1. Cash flow must support the financing.
For rental properties, investors should carefully evaluate rental income, operating expenses, debt service, vacancy assumptions, maintenance, insurance, and property taxes.
A property that appears profitable under optimistic assumptions may become financially challenging when financing costs or operating expenses increase.
2. Debt-service coverage matters.
Investors using Debt Service Coverage Ratio (DSCR) loans should examine whether a property's qualifying rental income adequately supports its proposed debt payments.
Lenders have different underwriting requirements, but understanding the property's debt-service coverage can help investors determine whether an acquisition is financially sustainable.
3. Maintain adequate reserves.
Unexpected repairs, vacancies, delayed renovations, and other operating expenses can create pressure even on otherwise sound investments.
Maintaining appropriate cash reserves can help investors manage these challenges without relying on additional borrowing.
4. Evaluate refinancing conservatively.
Some investors purchase properties with the intention of refinancing later if rates decline. While this strategy may work under favorable conditions, refinancing is never guaranteed.
Property values, rental income, credit requirements, lending guidelines, and future interest rates can all affect refinancing eligibility.
A successful investment should make financial sense under its initial financing structure rather than depending entirely on a future refinance.
Could Seller Financing Become More Attractive?
As traditional borrowing costs remain elevated, seller financing may be worth considering for certain real estate transactions.
Seller financing occurs when a property owner agrees to finance some or all of the purchase price rather than requiring the buyer to obtain the entire amount through a conventional lender.
Depending on the transaction, the parties may negotiate the down payment, interest rate, repayment schedule, maturity date, and other terms.
For sellers, this arrangement may expand the pool of potential buyers and create an opportunity to receive interest income.
For qualified buyers and investors, it may provide an alternative route to acquiring a property when conventional financing is expensive, restrictive, or difficult to obtain.
However, seller financing is not automatically cheaper or safer than a traditional mortgage. The interest rate, repayment obligations, collateral, existing liens, and potential balloon payment must all be carefully evaluated.
Both parties should obtain appropriate legal and financial guidance before entering into an agreement.
Private lending can also play a role in certain investment transactions, including eligible fix-and-flip projects, bridge financing, rental property acquisitions, and commercial real estate investments. Availability and terms depend on the lender, property, borrower, and overall project.
For investors who are exploring financing alternatives, comparing multiple structures may reveal options that better align with their investment strategy and cash-flow requirements.
Why Investors Should Pay Attention to the Bond Market
Mortgage rates do not move in isolation.
The bond market, particularly the yield on the 10-year U.S. Treasury note, is an important indicator to watch because long-term mortgage rates are influenced by similar expectations about inflation, economic growth, and future interest rates.
When investors become concerned about persistent inflation, Treasury yields may rise, putting upward pressure on mortgage rates. When inflation concerns ease or investors seek the relative safety of government bonds, Treasury yields may decline, potentially creating room for mortgage rates to move lower.
These relationships are not exact, and mortgage rates can move differently from Treasury yields because lenders and investors also account for credit risk, prepayment risk, and other market factors.
For real estate investors, monitoring these broader financial trends can provide useful context when evaluating financing options.
Nevertheless, attempting to predict the precise timing of interest-rate movements can be difficult. Investors should focus on acquiring properties with sound fundamentals and financing structures that can withstand changing market conditions.
What Should Homebuyers Do Now?
For prospective homebuyers, a small weekly decline in mortgage rates may be encouraging, but it should not be the sole reason to enter the market.
Buyers should begin by establishing a realistic budget, reviewing their credit profiles, comparing lender offers, and determining how much they can comfortably afford each month.
It is also important to compare the annual percentage rate (APR), lender fees, discount points, closing costs, and other loan terms rather than focusing exclusively on the advertised interest rate.
Some buyers may benefit from purchasing now if they find the right property at a reasonable price and can comfortably manage the payment. Others may need additional time to save for a down payment, reduce debt, or improve their credit.
There is no single strategy that works for every household.
The goal should be to make a financially sound decision based on individual circumstances rather than trying to predict the exact bottom of the mortgage market.
Looking Ahead: Preparation Is More Important Than Prediction
As the Federal Reserve prepares to announce its next decision, the real estate market remains sensitive to inflation, borrowing costs, and changing economic expectations.
The recent decline in mortgage rates is welcome news, but it does not yet establish a sustained downward trend. Buyers and investors should remain cautious about assuming that financing will become significantly less expensive in the coming months.
For real estate investors, the current environment reinforces the importance of disciplined underwriting, realistic cash-flow projections, adequate reserves, and access to suitable financing options.
For homebuyers, it is an opportunity to review budgets, compare mortgage products, and prepare to act when the right property and financing terms align.
My perspective is simple: Successful real estate investing is not about predicting every movement in interest rates. It is about understanding the numbers, managing risk, and making informed decisions that support your long-term financial goals.
Whether you are purchasing your first home, expanding a rental portfolio, or exploring commercial real estate opportunities, preparation and sound financial planning remain essential in any market.