A Nonperforming Loan Isn’t Necessarily a Failed Asset
How to Transform Distressed Mortgage Notes Into Profitable Investments Through Strategic Analysis and Compassionate Problem-Solving

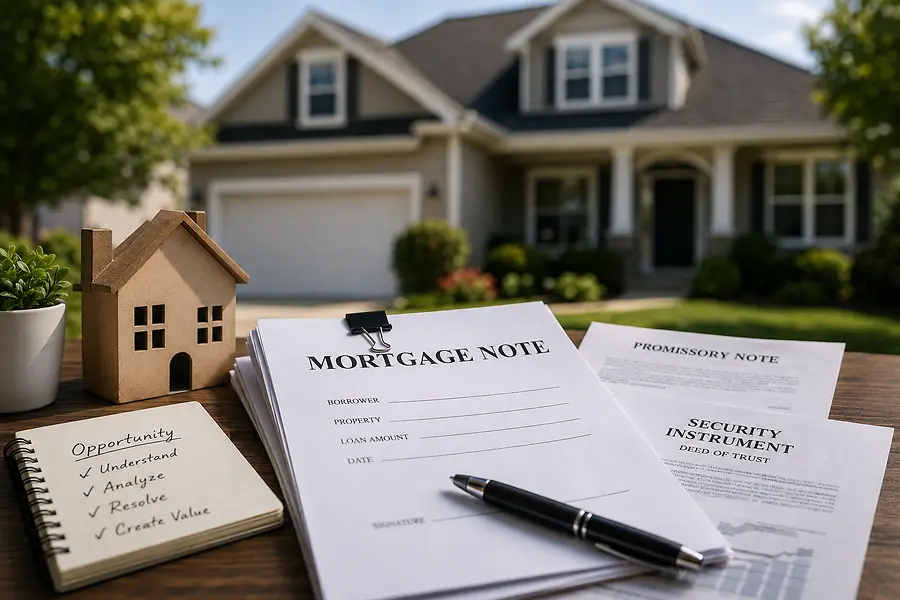
Seeing Opportunity in Distressed Assets
When most people hear that a mortgage loan is "nonperforming," they naturally assume something has gone wrong. The borrower has stopped making payments, the loan is distressed, and legal action may eventually become necessary. From the outside, it can easily look like a failed investment.
After nearly two decades in mortgage-note investing, I have learned to see these situations differently. A nonperforming loan isn't necessarily a failed asset. Sometimes, it is simply an unresolved situation.
That distinction has shaped the way I invest, the questions I ask, and the way I evaluate risk and opportunity. Mortgage-note investing has taught me that the initial condition of an asset does not always determine its ultimate outcome. What matters is understanding the full picture and identifying the right path forward.
Looking Beyond the Property
I began investing in mortgage notes in 2008 after building experience in traditional real estate through fixer-uppers, condominium conversions, and development projects. What attracted me to mortgage notes was the opportunity to look beyond the physical property and understand the debt behind it.
A mortgage note requires you to evaluate many different components at the same time: the borrower, the collateral, lien position, payment history, servicing records, title, legal documentation, property value, and the various ways a loan might ultimately be resolved. Two loans can look remarkably similar on a spreadsheet and yet produce entirely different outcomes.
That complexity is exactly what interested me. It requires both analytical discipline and creative problem-solving. Over time, I learned that successful note investing is not simply about purchasing distressed debt at an attractive price. The real value is often created through understanding the asset better than it was understood before.
When the Expected Outcome Changes
One investment in particular reinforced that lesson.
We acquired a nonperforming second mortgage for approximately $2,000. From the beginning, we understood that there was a first mortgage ahead of our lien. That senior debt was part of our underwriting before we ever purchased the note, and we evaluated the investment knowing that any foreclosure on our second mortgage would result in our taking the property subject to that first lien.
The borrower did not resume payments, and after other resolution efforts were unsuccessful, we eventually proceeded through the legal process and foreclosed on the second mortgage.
When we took ownership of the property, our expectation was straightforward: we would now have to address the existing first mortgage and begin dealing with the senior lender accordingly.
Instead, we learned something unexpected. The first-mortgage lender had previously charged off the loan, and further review ultimately confirmed that the senior mortgage no longer encumbered the property. As a result, what began as the purchase of a deeply discounted junior mortgage ultimately resulted in ownership of a property worth more than $200,000, free and clear of the senior lien we had expected to remain in place.
It was an extraordinary outcome, and certainly not one I would suggest is typical of mortgage-note investing. But the experience reinforced an important principle: good underwriting prepares you for the expected outcome, while experience helps you recognize opportunity when the outcome changes.
The lesson was not simply that a $2,000 investment produced an unusually valuable asset. The deeper lesson was that distressed-debt investing requires investors to remain attentive throughout the entire life of the investment. Circumstances can evolve, new information can emerge, and the strategy that made sense when a note was purchased may not be the same strategy that ultimately creates the best result.
When Communication Creates the Resolution
Not every successful note resolution ends with foreclosure or taking ownership of the property. In fact, many of the most meaningful outcomes I have experienced have come from establishing communication with borrowers and understanding why the loan became nonperforming in the first place.
Over the years, we have acquired many loans where borrowers had stopped making payments. On paper, those loans appeared distressed. Once communication was established, however, we frequently discovered that a significant life event had disrupted the borrower's financial circumstances.
Some borrowers had experienced serious health problems. Others had gone through a divorce, lost a job, or encountered another major financial setback. These circumstances did not eliminate the debt, nor did they eliminate our responsibility as investors to protect the investment. But they did provide important information that helped us evaluate whether a realistic resolution was possible.
When the borrower's circumstances supported it, we worked to create loan modifications with payment terms the borrower could reasonably afford. The goal was not simply to obtain a temporary payment or create an agreement that would fail again several months later. A successful modification has to be sustainable.
In many of these situations, borrowers resumed payments, and loans that had previously been classified as nonperforming returned to performing status. The borrower was able to remain in the home and rebuild financial stability, while the investor converted a distressed asset back into an income-producing loan. At the same time, the costs, time, and uncertainty associated with foreclosure could often be avoided.
These experiences have taught me that sometimes one of the most valuable tools available to a distressed-debt investor is communication. Good asset management requires knowing the difference between a situation that cannot realistically be resolved and one in which the borrower simply needs a workable path forward.
That distinction is not always visible in a spreadsheet. Sometimes, you have to understand the person and circumstances behind the loan.
Financial Discipline and Compassion Can Coexist
One of the principles that has become increasingly important to me is that financial discipline and compassion do not have to be mutually exclusive.
Mortgage-note investors still have responsibilities. We must protect the capital invested, evaluate collateral, understand lien priority, monitor legal costs, verify documentation, and make decisions based on sound financial analysis. Compassion cannot replace underwriting.
At the same time, treating a borrower professionally and respectfully does not weaken an investment strategy. In some cases, understanding the borrower's circumstances can actually help identify a better economic resolution.
The objective should not be to force every distressed loan into the same strategy. Some loans can be modified. Some borrowers can reinstate. Some situations are better resolved through settlement or payoff, while others ultimately require foreclosure. Experience teaches you not only what tools are available, but when each one is appropriate.
What Distressed Assets Have Taught Me
Mortgage-note investing has changed the way I think about opportunity more broadly. When something does not perform as expected, our instinct is often to label it a failure. I have learned instead to examine what changed, what information may be missing, what assumptions are being made, and what possibilities still remain.
That does not mean every distressed asset contains a hidden windfall. It means that an investor should understand the situation thoroughly before deciding what the outcome must be.
Some of my greatest lessons have come from investments that became more complicated than expected. Title issues, servicing problems, legal complexities, lien questions, and borrower circumstances can all change the direction of an investment. Those experiences have made me more disciplined about due diligence and more comfortable asking questions, even when experienced professionals are sitting on the other side of the table.
Over time, I have come to believe that expertise does not mean having every answer. Often, expertise means knowing which questions still need to be asked, recognizing when circumstances have changed, and being willing to adjust your strategy accordingly.
Seeing Opportunity Differently
Mortgage-note investing has taught me patience, discipline, and the importance of looking beneath the surface. It has also reinforced something I have experienced repeatedly throughout my entrepreneurial journey: the situation you inherit does not always determine the outcome you ultimately create.
A nonperforming loan may eventually require foreclosure. It may return to performing status through a well-structured modification. An unexpected change in a senior lien may completely alter the economics of an investment. There is no single resolution that fits every distressed asset.
What matters is understanding the facts, maintaining financial discipline, communicating when appropriate, and remaining open to possibilities that may not have been obvious at the beginning.
For me, that is one of the most valuable lessons this industry has provided:
The value of a distressed asset is not always defined by where it starts. Sometimes, it is determined by how deeply you understand the situation and what you are able to do next.