September 2026: The Real Estate Market Enters the Age of the Selective Buyer
How changing interest rates and creative financing strategies are reshaping opportunities for real estate investors in the fall market.

September 2026 Real Estate: The Rules of the Game Are Changing
September 2026 may mark an important turning point for the U.S. economy and real estate market—not because the market is about to collapse, and not because a dramatic boom is beginning, but because the rules of the game are changing.
For the remainder of 2026, money is likely to remain expensive, buyers will remain selective, and opportunities will increasingly favor investors who understand financing, cash flow, and creative deal structures.
The biggest question entering September is interest rates.
The Federal Reserve is scheduled to meet September 15–16, and the market has rapidly increased the probability of another rate hike following Federal Reserve Chair Kevin Warsh's recent comments about inflation. As of August 31, market expectations put the probability of a September increase near 60%–66%.
That is a major change from the rate-cut narrative many investors expected earlier this year.
The Economy: Growth Continues, But the Margin for Error Is Getting Smaller
The U.S. economy is entering September with conflicting signals.
Employment has remained resilient, but recent labor-market data have softened. At the same time, inflation remains a concern, while higher energy prices and geopolitical uncertainty are creating additional pressure on consumers and businesses.
That leaves the Federal Reserve with a difficult choice: fight inflation aggressively or protect an economy showing signs of slowing.
The outcome of that decision could determine the direction of financial markets, commercial lending, and residential real estate throughout the fall.
For real estate investors, however, there is an important distinction:
The Federal Reserve does not directly set mortgage rates.
Mortgage rates are heavily influenced by Treasury yields, inflation expectations, and bond-market conditions. That means even if the Fed eventually begins cutting short-term rates, mortgage and commercial borrowing costs may not fall nearly as quickly as investors expect.
As of August 31, the average 30-year mortgage rate was roughly 6.7%, remaining close to the highest levels of the year.
That reality is likely to define September.
Residential Real Estate: More Negotiating Power, But Not a Fire Sale
The residential housing market is becoming more balanced.
July brought a sharp decline in new-home sales, which fell 10.5% to an annualized rate of 607,000. The median new-home price fell to approximately $393,800, a four-year low.
Housing starts also weakened, with single-family starts falling nearly 10% in July.
But this does not necessarily mean a nationwide housing crash is coming.
The country still faces a structural shortage of housing in many markets, while millions of existing homeowners remain locked into mortgages obtained at substantially lower rates. That has kept many homeowners from selling.
The result is an unusual market:
Sales volumes are weak, but prices remain relatively strong.
J.P. Morgan expects U.S. home prices to remain roughly flat during 2026 before potentially increasing about 3% in 2027.
Realtor.com has taken a more conservative view, forecasting only 1.2% home-price growth for 2026 while expecting existing-home sales to increase modestly.
September therefore looks less like a buyer's crash market and more like a negotiation market.
Buyers have more choices in many areas. Properties are taking longer to sell. Sellers are increasingly being forced to consider concessions, price reductions, or alternative financing.
That creates opportunity.
The Real Estate Investor May Have More Leverage Than the Homebuyer
The most interesting part of the September market may not be traditional residential real estate.
It may be the growing opportunity in commercial real estate and investment properties.
Higher interest rates have made refinancing more difficult. Owners with loans coming due may discover that replacing an older loan with today's financing produces significantly higher debt-service requirements.
That can create motivated sellers.
A property that looked perfectly profitable five years ago may have a completely different financial profile when the owner has to refinance at today's rates.
For investors with liquidity, strong financing relationships, and patience, this creates an important advantage:
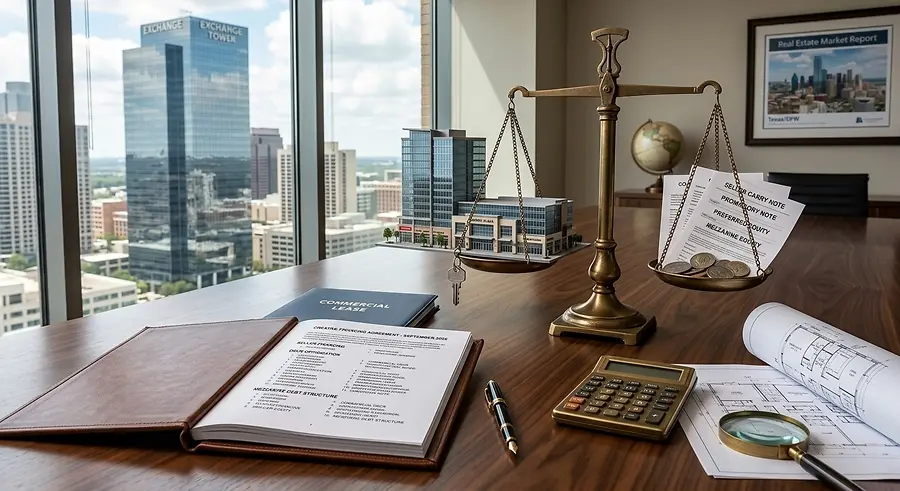
The opportunity may not be buying cheaper real estate. The opportunity may be creating better financing.
Seller Financing Could Become More Important
September could accelerate the return of one of the oldest tools in real estate: seller financing.
When conventional financing becomes expensive or difficult, sellers who are willing to carry part of the purchase price can make otherwise difficult transactions possible.
Instead of requiring a buyer to finance 100% of the acquisition through a bank, a transaction can potentially combine:
- A first-position commercial or DSCR loan
- A buyer's down payment
- Seller financing
- Seller equity
- Preferred equity
- Structured subordinate debt
The exact structure must be evaluated by lenders, attorneys, and tax professionals, but the concept is increasingly important.
The seller may receive monthly income.
The buyer may obtain control of an income-producing asset without relying entirely on traditional bank financing.
And the lender may have a stronger capital structure because the transaction is designed around the property's actual cash flow.
In a high-rate environment, creative financing isn't necessarily a sign that a deal is weak. It can be the reason a good deal works.
Commercial Real Estate: The Weakest Assets Will Become More Vulnerable
Commercial real estate will likely remain divided into winners and losers.
High-quality properties with strong tenants, good locations, and reliable cash flow should continue to attract capital.
Properties with weak occupancy, excessive leverage, outdated buildings, or unrealistic valuations will face greater pressure.
Office real estate remains particularly vulnerable, while industrial, logistics, data-center-related infrastructure, hospitality in strong markets, and other income-producing sectors may continue to attract investor interest.
The key metric will increasingly be cash flow rather than headline valuation.
Investors should ask:
Does the property produce enough income to support today's debt?
If the answer is no, the property's previous valuation may not matter.
Hotels, RV Parks, Self-Storage, and Operating Businesses Could Become Particularly Interesting
One of the most important trends for investors entering September is the convergence of real estate and operating businesses.
An investor buying a hotel, RV park, marina, car wash, laundromat, or other operating business with real estate attached isn't simply buying a building.
They are buying a cash-flowing business secured by real estate.
That distinction becomes extremely important when interest rates are high.
A vacant building may struggle to justify today's financing costs.
An operating property with strong historical revenue, predictable expenses, and sustainable cash flow may have a much better chance of supporting debt.
This is why investors should increasingly focus on NOI, EBITDA, DSCR, occupancy, margins, and debt structure—not simply purchase price.
Texas May Remain an Important Investment Market
Texas enters September with an economy that continues to show resilience.
Texas added jobs through the middle of 2026, although economic conditions remain sensitive to interest rates, energy prices, and broader national trends.
Markets such as Dallas-Fort Worth, Houston, Austin, and San Antonio remain important real estate markets, but investors should be careful about treating Texas as one single market.
The economics of a Dallas multifamily property can be dramatically different from those of a rural Texas RV park, hotel, or industrial property.
The best opportunities will increasingly be asset-specific rather than simply market-specific.
What September Could Mean for Buyers
September may be one of the better months in recent years for buyers who are prepared to negotiate.
Buyers should not assume that every seller is motivated.
But they should recognize that sellers facing higher refinancing costs, aging assets, declining occupancy, or changing business conditions may have significantly more flexibility than their asking prices suggest.
The strongest buyers will likely be those who can demonstrate:
Proof of funds.
Strong financials.
A credible financing structure.
Fast due diligence.
A realistic closing strategy.
In this environment, certainty can be worth almost as much as price.
What September Could Mean for Sellers
Sellers may need to adjust their expectations.
The days of assuming that every property will automatically receive multiple offers at an aggressive valuation are not universal anymore.
Properties with strong financial performance can still command premium valuations.
Properties with weak financials may require creativity.
Seller financing, interest-rate buydowns, price adjustments, earnouts, equity participation, and other structures may become increasingly important tools for getting transactions completed.
A seller who refuses every financing alternative may eventually discover that the buyer who offered less money—but presented a workable structure—was actually the stronger offer.
The Bottom Line: September Will Reward the Prepared
The biggest mistake investors can make in September 2026 is waiting for the market to tell them exactly what is going to happen.
Nobody knows whether the Federal Reserve will raise rates in September, hold them steady, or change direction later in the year.
Nobody knows exactly where Treasury yields will finish the year.
Nobody knows whether housing prices will rise or fall in every individual market.
But investors can control how they underwrite a deal.
They can demand accurate financials.
They can stress-test debt.
They can analyze DSCR.
They can negotiate purchase prices.
They can structure seller financing.
They can walk away from deals that don't work.
And they can move quickly when the right opportunity appears.
September 2026 is unlikely to be a market for the investor who simply buys what is available.
It may be a market for the investor who finds the property with the right cash flow, the right seller, the right financing, and the right structure.
The real opportunity may not be waiting for interest rates to fall.
The opportunity may be learning how to make deals work while rates remain elevated.
That could make the second half of 2026 one of the most interesting periods for disciplined real estate investors in years.