Why Every Growing Business Needs a Board — Even a Family One
How a Simple Board of Advisors Can Transform Your Business Decision-Making
When I talk with business owners about growth, the conversation almost always turns to the big, visible things—sales, marketing, and hiring the next employee. Rarely does anyone bring up something quieter but just as powerful: who is actually helping you think through the direction of your business?
A formal Board of Directors is one of the most underused tools available to privately held and family-run businesses. It doesn't have to look like a Fortune 500 boardroom. For many owners, it starts with the people who already know the business best—a spouse, an adult child, a trusted advisor, or someone whose judgment you respect—brought together on a regular schedule to ask hard questions and offer real input.
It's About More Than a Signature on a Resolution
A board does more than check a compliance box. Done well, it changes the way a business operates. It creates a standing appointment to step back from the day-to-day and look at the business the way an outside investor would: Is this strategy still working? Where are the blind spots? What decisions have we been putting off?
For business owners who have spent years making every call alone, this shift can feel uncomfortable at first. I'd encourage you to sit with that discomfort rather than avoid it. Some of the best decisions I've seen clients make came out of a meeting where someone on their board asked a question they didn't want to answer.
Who Belongs on a Board Like This
A board built around family members or close advisors works when everyone on it has a real role to play—reviewing financials, weighing in on growth plans, or helping think through a key decision facing the business. It is not simply a title handed out to a relative. The IRS and the courts have been clear on this point: compensation must be reasonable, duties must be legitimate, and the whole arrangement has to reflect how a business actually runs, not just how it's structured on paper.
That said, when the roles are real, this structure can also open the door to shifting some income toward family members who are in a lower tax bracket, which can mean meaningful savings for the household as a whole, alongside the strategic value the board provides.
What Makes It Hold Up
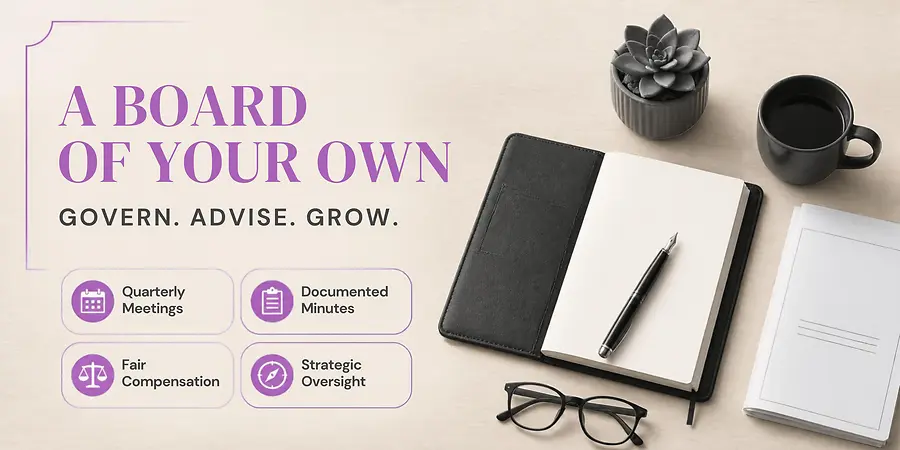
Every board, family-run or otherwise, needs a foundation of documentation: a board resolution establishing the group, an agenda for each meeting, and minutes that record who attended and what was discussed and decided. Meetings should happen on a regular cadence—quarterly is the standard most advisors recommend—and compensation for each director should be reasonable for the role, consistent with what you'd expect to pay someone outside the family for similar oversight and expertise.
Where a board meets matters less than most people assume, as long as the business purpose is clear and documented. A meeting held somewhere other than your home office is still a legitimate business meeting when it's run like one.
A Step Worth Taking Seriously
If you've been running your business as a one-person decision-making operation, consider this an invitation to change that. Bringing the right people into a structured, recurring conversation about your business is one of the more generous things you can do for your company's future—and often, for your family's financial future as well.
As with any strategy tied to compensation, documentation, and tax treatment, the details matter, and they're specific to your business structure and circumstances. This is a conversation worth having with your tax advisor before you put a board in place, so the structure you build is one that holds up and genuinely serves your business.
Daisy Taylor is the founder of TR Business & Tax LLC, a tax strategy and advisory firm based in Montgomery, Alabama, dedicated to helping business owners and high-income professionals — including physicians, dentists, and entrepreneurs — legally reduce their tax burden and build long-term wealth. Daisy's path to entrepreneurship was built on nearly twenty years of high-stakes financial leadership. As a senior…